TOTAL LOSS EXPLAINED
What Insurance Companies Don't Tell You About Your Totaled Car.
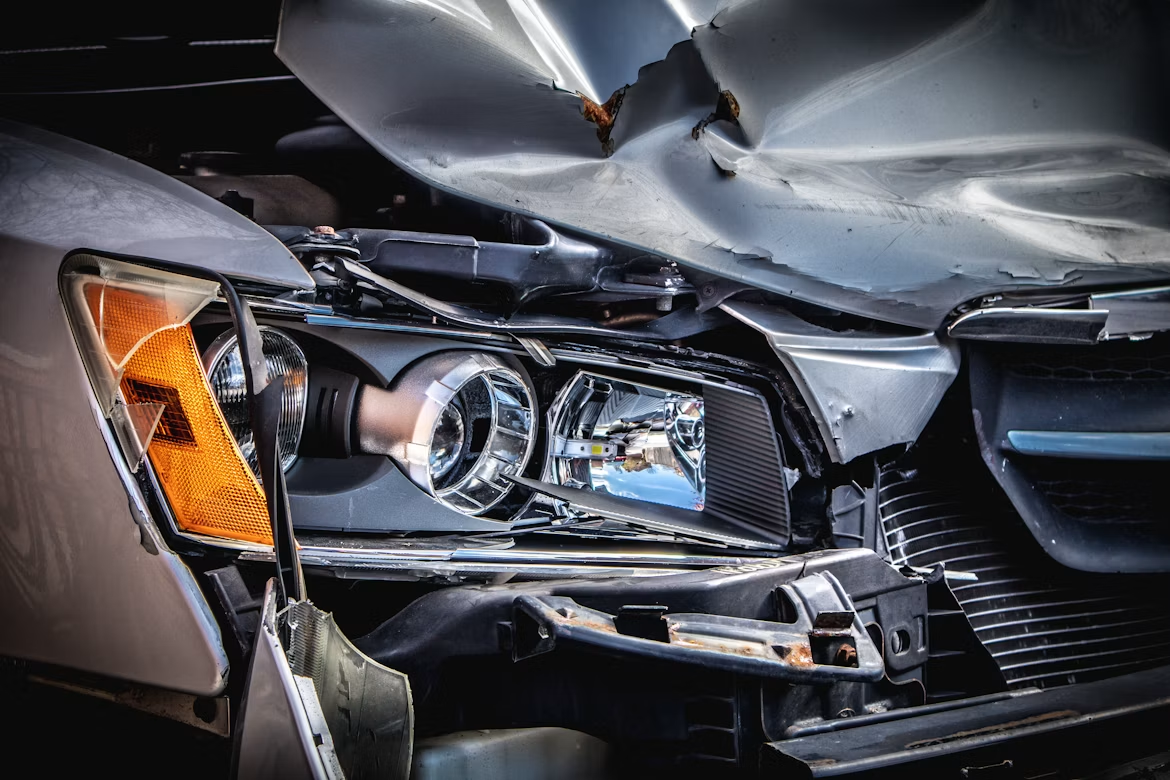
A total loss is a financial decision, not a mechanical one. Your car may still run, may still look repairable, and may not be destroyed. What matters is whether the insurer’s formula says the vehicle costs too much to repair compared to its calculated value.
THE BASICS
What Counts as a Total Loss?
A vehicle is totaled when repairing it stops making financial sense to the insurer. Here are a few things that surprise most owners:
- A total loss vehicle does not need to be destroyed.
- Many totaled vehicles are still drivable.
- The decision is financial, not mechanical.
- The threshold varies by state and insurer.
THE BASICS
Find out if the insurer’s offer is fair before spending a dime.
Repair Cost + Salvage Value > Actual Cash Value
- If the equation holds, the car is legally a total loss. Common errors include inflated salvage values, padded repair estimates, incorrect condition ratings and mismatched comparables.
THE KEY NUMBER
What is Actual Cash Value?
Actual Cash Value (ACV) is the fair market value of your vehicle immediately before the loss.
ACV is not:
- What you paid for the car
- Your loan balance
- The Kelley Blue Book trade-in figure
- The cost to replace it with a similar vehicle
Insurers calculate ACV using third-party vendors like CCC One, Mitchell and Audatex. The output is only as good as the comparables and adjustments applied.
This is where most undervaluation happens.
THE BASICS
What Counts as a Total Loss?
A vehicle is totaled when repairing it stops making financial sense to the insurer. Here are a few things that surprise most owners:
Insurer Offer
$16,500. Based on mismatched trims, higher mileage and lower condition ratings.
Independent Appraisal
$19,750. Supported by properly matched comparables and corrected adjustments.
GET THE FACTS
Don't Leave Thousands on the Table.
Get an independent review of your total loss valuation.